Key takeaways
- SAFE notes offer startups a simple, quick, and lower-cost method to raise seed funding compared to traditional convertible notes.
- Unlike convertible notes, SAFEs are not debt instruments—therefore they don’t accrue interest or require repayment by a maturity date.
- Investors often prefer convertible notes due to additional protections such as liquidation preferences and interest accrual.
- SAFEs are more suitable for incorporated businesses, as they convert into equity—an option unavailable for LLCs.
- Choosing between a SAFE and a convertible note depends on your startup goals, entity structure, and investor expectations.
Links to outside sources open in a new tab.
It can be difficult for an entrepreneur to obtain seed money for a new startup. Investors want to see a valuation for the company. However, without initial capital investments, getting the company off the ground to create value might be difficult. Startups are turning to SAFE notes to solve this problem. Our Maryland business lawyer discusses the differences between SAFEs and convertible notes to help you decide which financing option is best for your business.
What Is a Simple Agreement for Future Equity (SAFE) Note?
Many entrepreneurs might not have heard about SAFE notes. They are a relatively new way to obtain seed investments for a startup. SAFE notes were created in 2013 by the Silicon Valley accelerator, Y Combinator. SAFEs are short contracts that let the investor purchase shares of the company in a future priced round. Valuation caps are typically the only contract term negotiated by the parties.
SAFEs and convertible notes have advantages and disadvantages. However, before we discuss those, let’s review the similarities and differences between SAFEs and convertible notes.
Similarities and Differences Between Convertible Notes and SAFEs
First, let’s look at how these security instruments are alike.
- Each investment option gives the startup seed money
- The investor may convert their investment into equity in a later financing round
- SAFEs and convertible bonds use caps and discounts as conversion features for investors
Second, let’s discuss some differences between convertible notes and SAFEs:
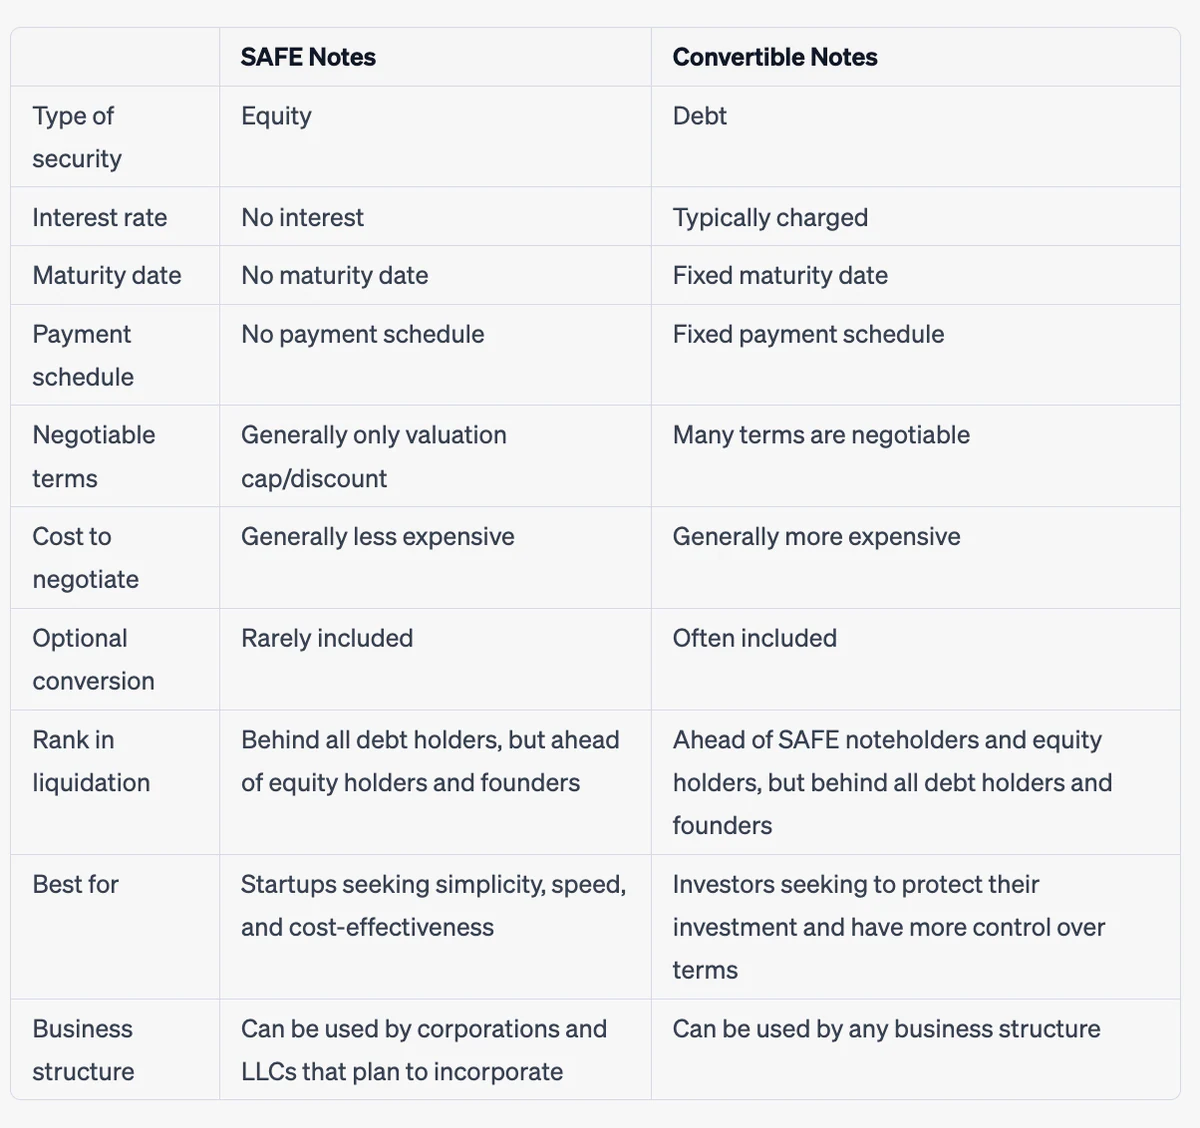
- SAFEs are not debt. The business owner need not list a SAFE on their balance sheet under liabilities. Therefore, SAFEs do not have interest, maturity dates, or payment schedules. Convertible notes are debts with fixed maturity dates and might charge interest on the outstanding balance.
- Convertible notes have many terms that can be negotiated between the parties. In contrast, the terms in a SAFE note are generally fixed, except for the cap or discount amount.
- A SAFE note can be less costly to negotiate, draft, and execute because the contracts are typically shorter and less complex than a convertible note.
- A convertible note may include an optional conversion feature, rarely found in SAFE notes.
- Holders of convertible notes have preference over all equity holders because the convertible note is a debt instrument. So, the debt secured by a convertible note must be paid before amounts owed to SAFE noteholders, equity holders, and founders upon the sale of the business.
Whether to use a SAFE note or a convertible note depends on many factors. For example, your business type, goals, and other factors determine which option is best to fund your startup.
Should I Use Safe Notices or Convertible Notes to Fund My Startup?
The benefits of SAFEs, including simplicity, speed, cost, lack of interest rate, and no maturity date, favor the startup company. A SAFE note might be your best choice if you want to protect your interest in the company while securing investments in a simple, quick, and cost-effective manner.
Because SAFE notes are not debts, they do not count against you when valuing the company for future seed-found funding. Without a maturity date and interest to worry about, you are not working on a deadline to compensate the investor. Instead, the SAFE note relies only on trigger events to compensate the investor.
But interest rates, maturity dates, liquidation preferences, and optional conversions in a convertible note favor an investor. Therefore, investors might demand convertible notes to protect their investment in your company. A convertible note might seem to be a dead end for the startup when considering the advantages of SAFE notes.
However, depending on the amount the investor is willing to invest in your company as capital funds, you might opt to use a convertible note because the funds are worth more than the advantages of using a SAFE note.
Another issue is your company’s entity or business structure. SAFE notes are not debts, so they are on the capitalization table as stock options. However, only corporate entities have stock options. So, you must incorporate your business if you want to use SAFE notes instead of convertible notes. To maintain the ease of an LLC, you will need to use convertible notes for seed money instead of SAFE notes.
**Contact Our Maryland Business Attorney for More Information **
You are embarking on an exciting adventure. However, you need money to take your idea to the next level. Our Maryland business lawyer helps you review ways to raise capital to determine the best options for seed money. Contact Steve today to discuss your new business venture and how we can help protect your best interests while securing investors in your startup.
Start-Ups: Maximize Success & Minimize Risk
Everything founders need to launch on solid legal footing, from formation and finance to contracts and protecting your intellectual property.
Download free guide